
By Fintrovert · Last updated: October 24, 2026
The IRS has set the 2027 HSA contribution limits at $4,500 for self-only coverage and $9,000 for family coverage. That’s $100 more than 2026 for individuals and $250 more for families. Here’s what changed, who qualifies, and how to put the most money in.
1. 2027 HSA contribution limits at a glance
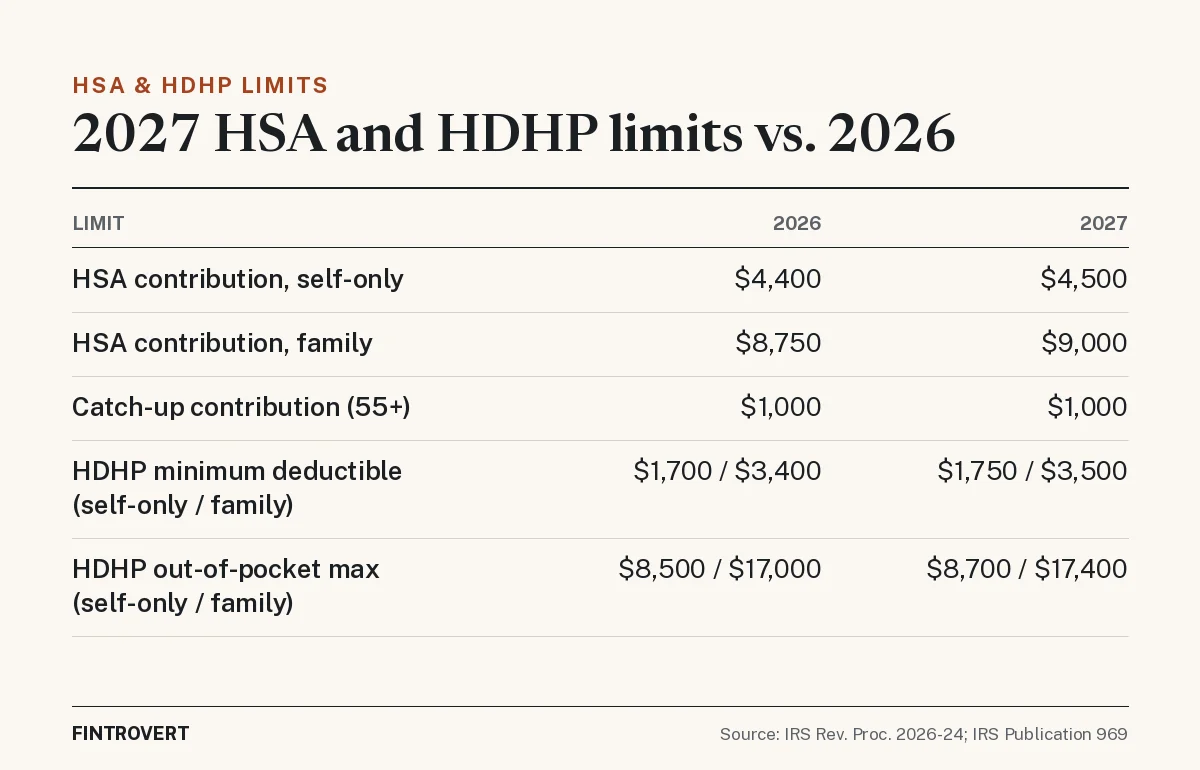
| Item | 2026 | 2027 |
|---|---|---|
| HSA limit, self-only | $4,400 | $4,500 |
| HSA limit, family | $8,750 | $9,000 |
| Catch-up (age 55+) | $1,000 | $1,000 |
| HDHP minimum deductible, self-only / family | $1,700 / $3,400 | $1,750 / $3,500 |
| HDHP out-of-pocket max, self-only / family | $8,500 / $17,000 | $8,700 / $17,400 |
Sources: IRS Rev. Proc. 2026-24 (2027) and IRS Publication 969 (2026). The limit covers everything that goes in from you and your employer combined.
2. 2027 high-deductible health plan rules
You can only contribute to an HSA if you’re covered by a qualifying high-deductible health plan (HDHP) and have no other disqualifying coverage. For 2027, the plan must have a deductible of at least $1,750 (self-only) or $3,500 (family), and out-of-pocket costs, not counting premiums, can’t go over $8,700 or $17,400.
You also can’t be enrolled in Medicare or be claimed as someone else’s dependent.
3. Age 55+ catch-up contributions
If you’re 55 or older by the end of the year, you can add an extra $1,000. That makes the 2027 ceiling $5,500 for self-only coverage and $10,000 for family coverage if only one spouse is 55+. If both spouses are 55 or older, each needs their own HSA to make a catch-up contribution, because the catch-up belongs to the person, not the plan.
Once you enroll in Medicare, you can’t contribute anymore. In that year, your limit is prorated by month.
4. The direct primary care change
The 2025 law known as the One, Big, Beautiful Bill Act changed the rules on direct primary care service arrangements (DPCSAs), where you pay a doctor’s practice a flat monthly fee. A DPCSA no longer disqualifies you from contributing to an HSA, provided the fees stay at or below a monthly cap. For 2027, that cap is $150 a month for one person or $300 a month if the arrangement covers more than one person (Rev. Proc. 2026-24).
5. HDHP vs. PPO: which one fits?
5.1 When an HDHP with an HSA tends to win
- You’re generally healthy and don’t expect large medical bills.
- Your employer puts money into your HSA.
- You have cash on hand to cover the deductible if something comes up.
5.2 When a PPO may be the better deal
- You have ongoing prescriptions, a planned surgery, or a pregnancy coming.
- Paying the deductible would put you under real financial strain.
Look at total cost: a year of premiums plus what you’d likely pay out of pocket, minus any employer HSA contribution and your tax savings.
6. Using your HSA as a retirement account
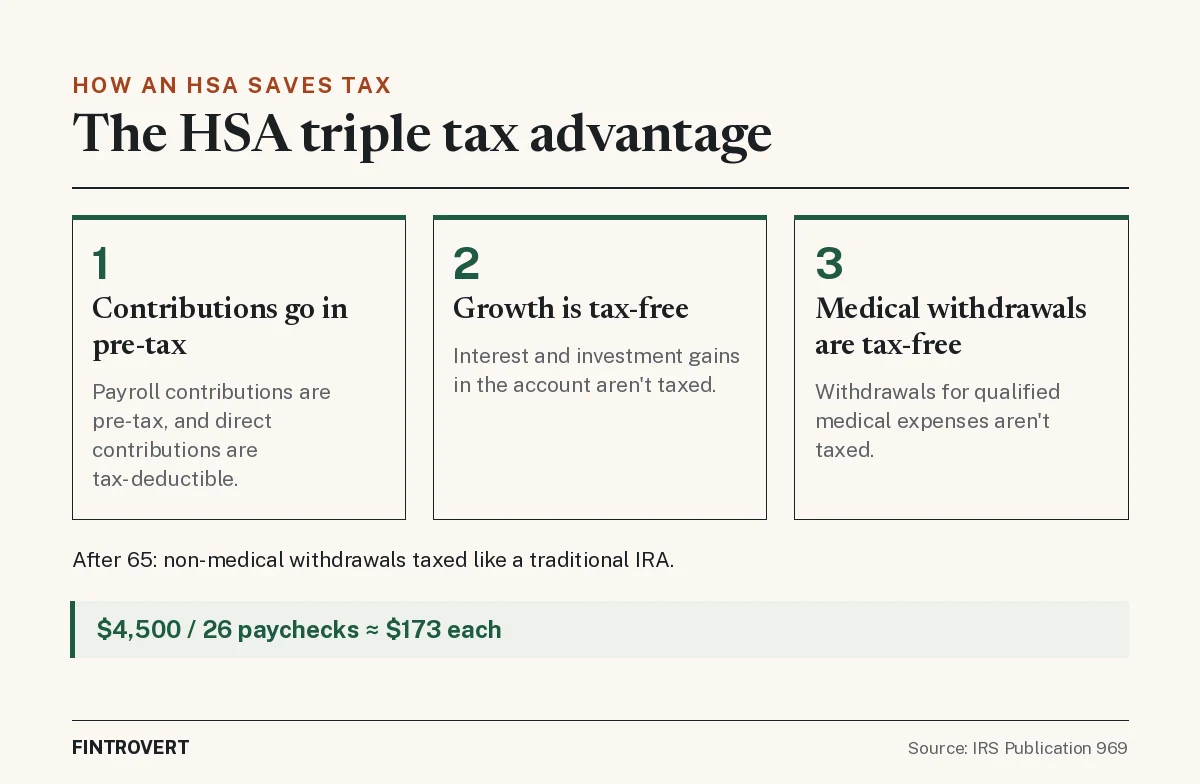
An HSA comes with three tax breaks. Contributions are deductible or pre-tax, growth isn’t taxed, and withdrawals for qualified medical expenses are tax-free. After age 65, you can take money out for any reason and pay only regular income tax, the same as with a traditional IRA (Pub 969).
If you can afford to pay current medical bills out of pocket, you can invest your HSA balance and let it grow. Keep your receipts, because there’s no deadline to reimburse yourself for a qualified expense incurred after the account was opened. If you’re new to investing, start with our guide to the basics of stock market investing in the USA. Thinking about getting help? Read how to choose a financial advisor in the USA.
7. How to max out your HSA in 2027
- Check your employer’s contribution and subtract it from your limit.
- Divide what’s left by your number of paychecks. For example, $4,500 over 26 paychecks is about $173 each.
- Contribute through payroll if you can. That also skips the 7.65% FICA tax.
- Add the $1,000 catch-up if you’re 55 or older.
- You can still make 2027 contributions up to the tax filing deadline in April 2028.
8. FAQs
What are the 2027 HSA contribution limits?
$4,500 for self-only coverage and $9,000 for family coverage, plus $1,000 if you’re 55 or older.
Do employer contributions count toward the limit?
Yes. Your contributions and your employer’s are added together.
Can I contribute if I’m on Medicare?
No. Once you’re enrolled, you can’t make new contributions, but you can still spend what’s already in the account.
Can I have direct primary care and an HSA?
Yes, as long as your fees in 2027 are $150 a month or less ($300 if the arrangement covers more than one person).
This article is for general information and isn’t tax advice. Figures are from the IRS sources linked above.